By Oru Leonard Oru

Nigeria’s growing appetite for borrowing has become one of the most important economic questions confronting the country. As the administration of President Bola Ahmed Tinubu continues to pursue ambitious economic reforms, infrastructure development and budgetary commitments, the increasing reliance on domestic and foreign loans raises fundamental questions about fiscal sustainability, economic priorities and the future of national development.
Borrowing, in itself, is not an economic crime. Governments across the world borrow to finance infrastructure, stimulate production, address fiscal deficits and support economic growth. Indeed, responsible borrowing can be an important instrument of national development.
However, the real issue is not simply how much a country borrows, but what it borrows for, how efficiently the money is utilised, what economic value it generates and whether the resulting benefits can justify the financial obligations imposed on present and future generations.
For Nigeria, these questions have become increasingly urgent.
THE ESCALATING DEBT PROFILE
Recent figures from Nigeria’s Debt Management Office indicate that the country’s total public debt stood at approximately ₦166.79 trillion as of June 30, 2026. This represents an increase of about ₦7.44 trillion compared with the first quarter of the year.
The debt portfolio comprises domestic and external obligations, with the Federal Government accounting for the overwhelming proportion.
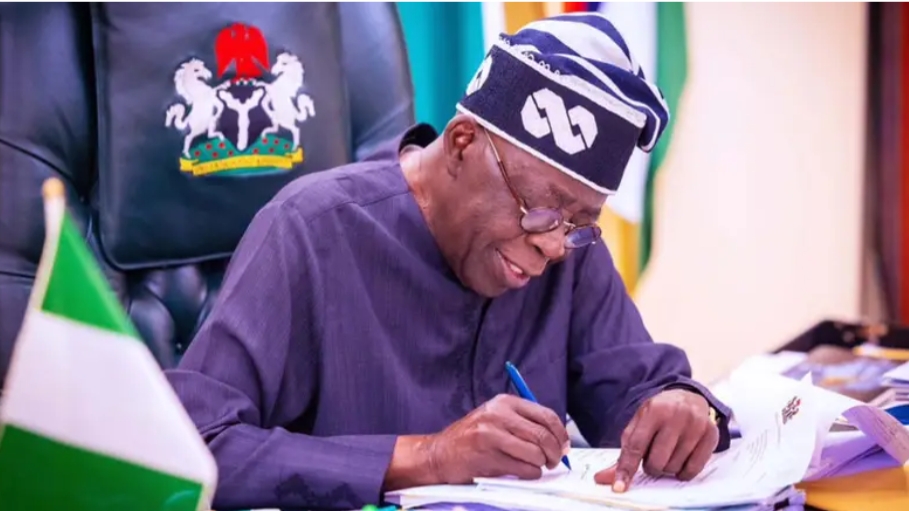
More recently, on November 4, 2026, President Tinubu requested legislative approval for approximately $7.7 billion in fresh external borrowing to finance components of the 2026 budget and government programmes. The request effectively replaces an earlier borrowing proposal of approximately $20.3 billion.
The development has once again brought the country’s borrowing strategy into the national conversation.
Nigeria’s 2026 budget, valued at ₦68.32 trillion, provides for approximately ₦15.8 trillion in debt servicing. This is a substantial financial commitment that illustrates the pressure existing debt obligations place on public finances.
The concern is that government must continue to borrow to finance development while simultaneously committing significant portions of its revenue to servicing loans already obtained.
This raises an important question: How much borrowing can Nigeria sustain without compromising its capacity to finance essential public services and stimulate productive economic activities?
THE COST OF BORROWING TO ORDINARY NIGERIANS
The implications of escalating public debt extend beyond government balance sheets. They eventually affect the economic and social conditions of ordinary Nigerians.
When a significant proportion of public revenue goes into interest payments and debt obligations, fewer resources may be available for critical sectors such as healthcare, education, agriculture, security, transportation, electricity and social welfare.
The consequences can be far-reaching.
Hospitals require modern equipment, qualified personnel and adequate funding. Schools and universities need infrastructure, research facilities and improved learning environments. Farmers require accessible financing, modern technology, storage facilities and reliable transportation networks.
Small and medium-sized enterprises need affordable credit, stable electricity, functional infrastructure and a predictable business environment.
When government finances become increasingly constrained by debt obligations, these sectors risk receiving inadequate attention.
There is also the danger that domestic borrowing could make it more expensive for private businesses to access credit. When government absorbs a substantial portion of available funds in the financial market, businesses may face higher borrowing costs or reduced access to financing.
This is particularly concerning in an economy where private-sector investment is urgently needed to generate employment, expand production and reduce poverty.
THE FOREIGN EXCHANGE DIMENSION
Nigeria’s external borrowing presents another important challenge.
Foreign loans are generally denominated in currencies such as the United States dollar. Consequently, fluctuations in the exchange rate can significantly increase the naira value of existing obligations.
A loan obtained when the exchange rate is relatively favourable may become substantially more expensive when the naira depreciates.
This creates an additional burden for a country whose revenue is largely collected in naira but whose external debt obligations must be serviced in foreign currency.
Nigeria therefore needs to strengthen its foreign exchange earnings through increased exports, industrialisation, agricultural production, solid minerals development, manufacturing and other productive sectors.
A country cannot indefinitely depend on foreign borrowing without building the productive capacity required to generate the foreign exchange necessary for repayment.
BORROWING MUST PRODUCE ECONOMIC VALUE
One of the most important considerations in assessing government borrowing should be the economic returns on borrowed funds.
If Nigeria borrows to construct functional highways, modernise railway infrastructure, improve electricity generation and distribution, develop agricultural value chains and expand industrial capacity, such investments can potentially generate economic benefits that extend beyond the repayment period.
However, borrowing becomes problematic when projects are poorly conceived, abandoned, inflated in cost or implemented without adequate economic justification.
The country must move beyond announcing loan approvals and budgetary allocations to demonstrating the actual impact of borrowed funds.
Every major borrowing arrangement should have clearly defined objectives, implementation timelines, measurable deliverables and transparent reporting mechanisms.
Nigerians deserve to know not only how much government borrows but also where the money goes, which projects benefit and what measurable economic returns are generated.
Accountability must not end with legislative approval of loans. It must extend to procurement, disbursement, project implementation and independent evaluation.
THE GOVERNMENT’S ARGUMENT AND THE NEED FOR BALANCE
The Tinubu administration has consistently presented its economic reforms as necessary measures to address longstanding structural weaknesses in the Nigerian economy.
The removal of fuel subsidies, foreign exchange reforms and efforts to improve revenue mobilisation have been defended as steps towards creating a more sustainable economic environment.
Government has also argued that borrowing is necessary because available revenue cannot adequately finance the country’s infrastructure requirements, recurrent expenditure and other national obligations.
There is an economic argument in favour of this position. Nigeria has enormous infrastructure deficits and development needs that cannot necessarily be addressed through annual revenue alone.
Nevertheless, the success of this approach must ultimately be measured by improvements in the living conditions of Nigerians, increased productivity, employment generation, industrial expansion and the quality of public infrastructure.
Economic reforms cannot be evaluated exclusively through macroeconomic indicators, government revenue figures or the confidence of international financial institutions.
The ordinary Nigerian must also experience tangible improvements in purchasing power, access to opportunities, affordable transportation, electricity supply and the cost of doing business.
The ultimate test of economic policy is its impact on the people.
NIGERIA MUST EXPAND ITS REVENUE BASE
Perhaps the more fundamental problem confronting Nigeria is not merely its borrowing appetite but its inability to generate sufficient revenue from its enormous economic potential.
Nigeria possesses significant opportunities in agriculture, solid minerals, manufacturing, tourism, information technology, maritime activities, aviation and the creative industries.
Yet, many of these sectors remain underdeveloped.
Rather than relying excessively on loans, government should intensify efforts to unlock these economic opportunities through strategic investments, public-private partnerships, improved tax administration and policies that encourage domestic and foreign investment.
The solid minerals sector, for instance, could become a significant source of revenue and employment if properly regulated, developed and integrated into local manufacturing.
Agriculture should move beyond subsistence production towards commercial farming, agro-processing, storage, packaging and export development.
Nigeria must also take advantage of international trade relationships to expand non-oil exports and attract productive investments.
Our economic diplomacy should therefore go beyond ceremonial engagements to practical trade agreements, technology transfers, industrial partnerships and market access.
These are areas where countries such as Bangladesh, India, Turkey and other emerging economies offer useful lessons in export-oriented development, manufacturing and SME growth.
WHAT SHOULD CHANGE?
There is a compelling need for a more disciplined national borrowing framework.
First, government should prioritise borrowing for productive capital investments rather than using loans to sustain avoidable recurrent expenditure.
Second, every major loan should be accompanied by a transparent project implementation and repayment framework.
Third, the National Assembly must exercise effective oversight by examining the terms, costs, beneficiaries and economic implications of proposed borrowing arrangements.
Fourth, government should strengthen independent monitoring of projects financed through borrowed funds and make implementation reports accessible to the public.
Fifth, Nigeria must urgently address its revenue-generation challenges by broadening the productive economy, reducing revenue leakages and improving the efficiency of public institutions.
Finally, government must develop a credible medium- and long-term debt management strategy that protects future generations from inheriting unsustainable financial obligations.
THE FUTURE CANNOT BE BUILT ON BORROWING ALONE
Nigeria stands at a critical point in its economic development. The country needs infrastructure, industrial expansion, quality education, improved healthcare, modern agriculture and an enabling environment for businesses.
These objectives require substantial financial resources, and borrowing may remain part of the financing equation.
However, borrowing cannot become a permanent substitute for economic productivity, effective governance and responsible fiscal management.
The danger is not simply that Nigeria is borrowing more money. It is that the country could find itself allocating an increasing proportion of its future revenues to obligations created today, thereby limiting the resources available for tomorrow’s development.
President Tinubu’s administration must therefore demonstrate that its borrowing decisions are supported by measurable economic benefits, transparent implementation and a realistic repayment strategy.
Nigeria must borrow to build productive capacity, not merely to postpone fiscal difficulties.
The real measure of successful borrowing is not the amount of money secured from international lenders or the volume of infrastructure announced in budget documents. It is the extent to which such borrowing improves the economy, expands opportunities, creates jobs, increases national revenue and improves the welfare of citizens.
Ultimately, Nigeria needs an economy that can finance a substantial proportion of its development from its own productive strength.
A nation cannot borrow its way permanently into prosperity. It must produce, manufacture, export, innovate and generate sufficient revenue to sustain its ambitions.
That is the economic conversation Nigeria must have now.
Oru Leonard Oru (frpa mnim), is a Media and Business Development Practioner based in Nigeria. Whatsapp: +234 8022426520. Email: oruleonard50@gmail.com